



About Indemnia
It started with a moving truck fire.
A 54-foot semi carrying everything we owned burned down mid-move. Nothing came back. The claim that followed is the one this company is built around.
What we were handed
A blank contents form, and a request to prove every line.
| Item | Bought | Paid |
|---|---|---|
| Television | Not known | Not known |
| Sofa | Not known | Not known |
| Winter coats (4) | Not known | Not known |
What happened
A claim with nothing left to look at
It was a personal-property claim with no structure claim attached. No adjuster walks a burned foundation and estimates your belongings for you. You are handed an empty schedule and asked to prove, line by line, what you owned, when you bought it and what it was worth.
We did that from memory and from whatever receipts could still be found. The hard part was not remembering the television. It was proving when it was bought and what it cost, and then doing that several hundred more times, for things nobody thinks to photograph.
Indemnia is what we built afterwards, for the version of us who had not started yet.
What we built
Three things that claim taught us
One
The record has to build itself
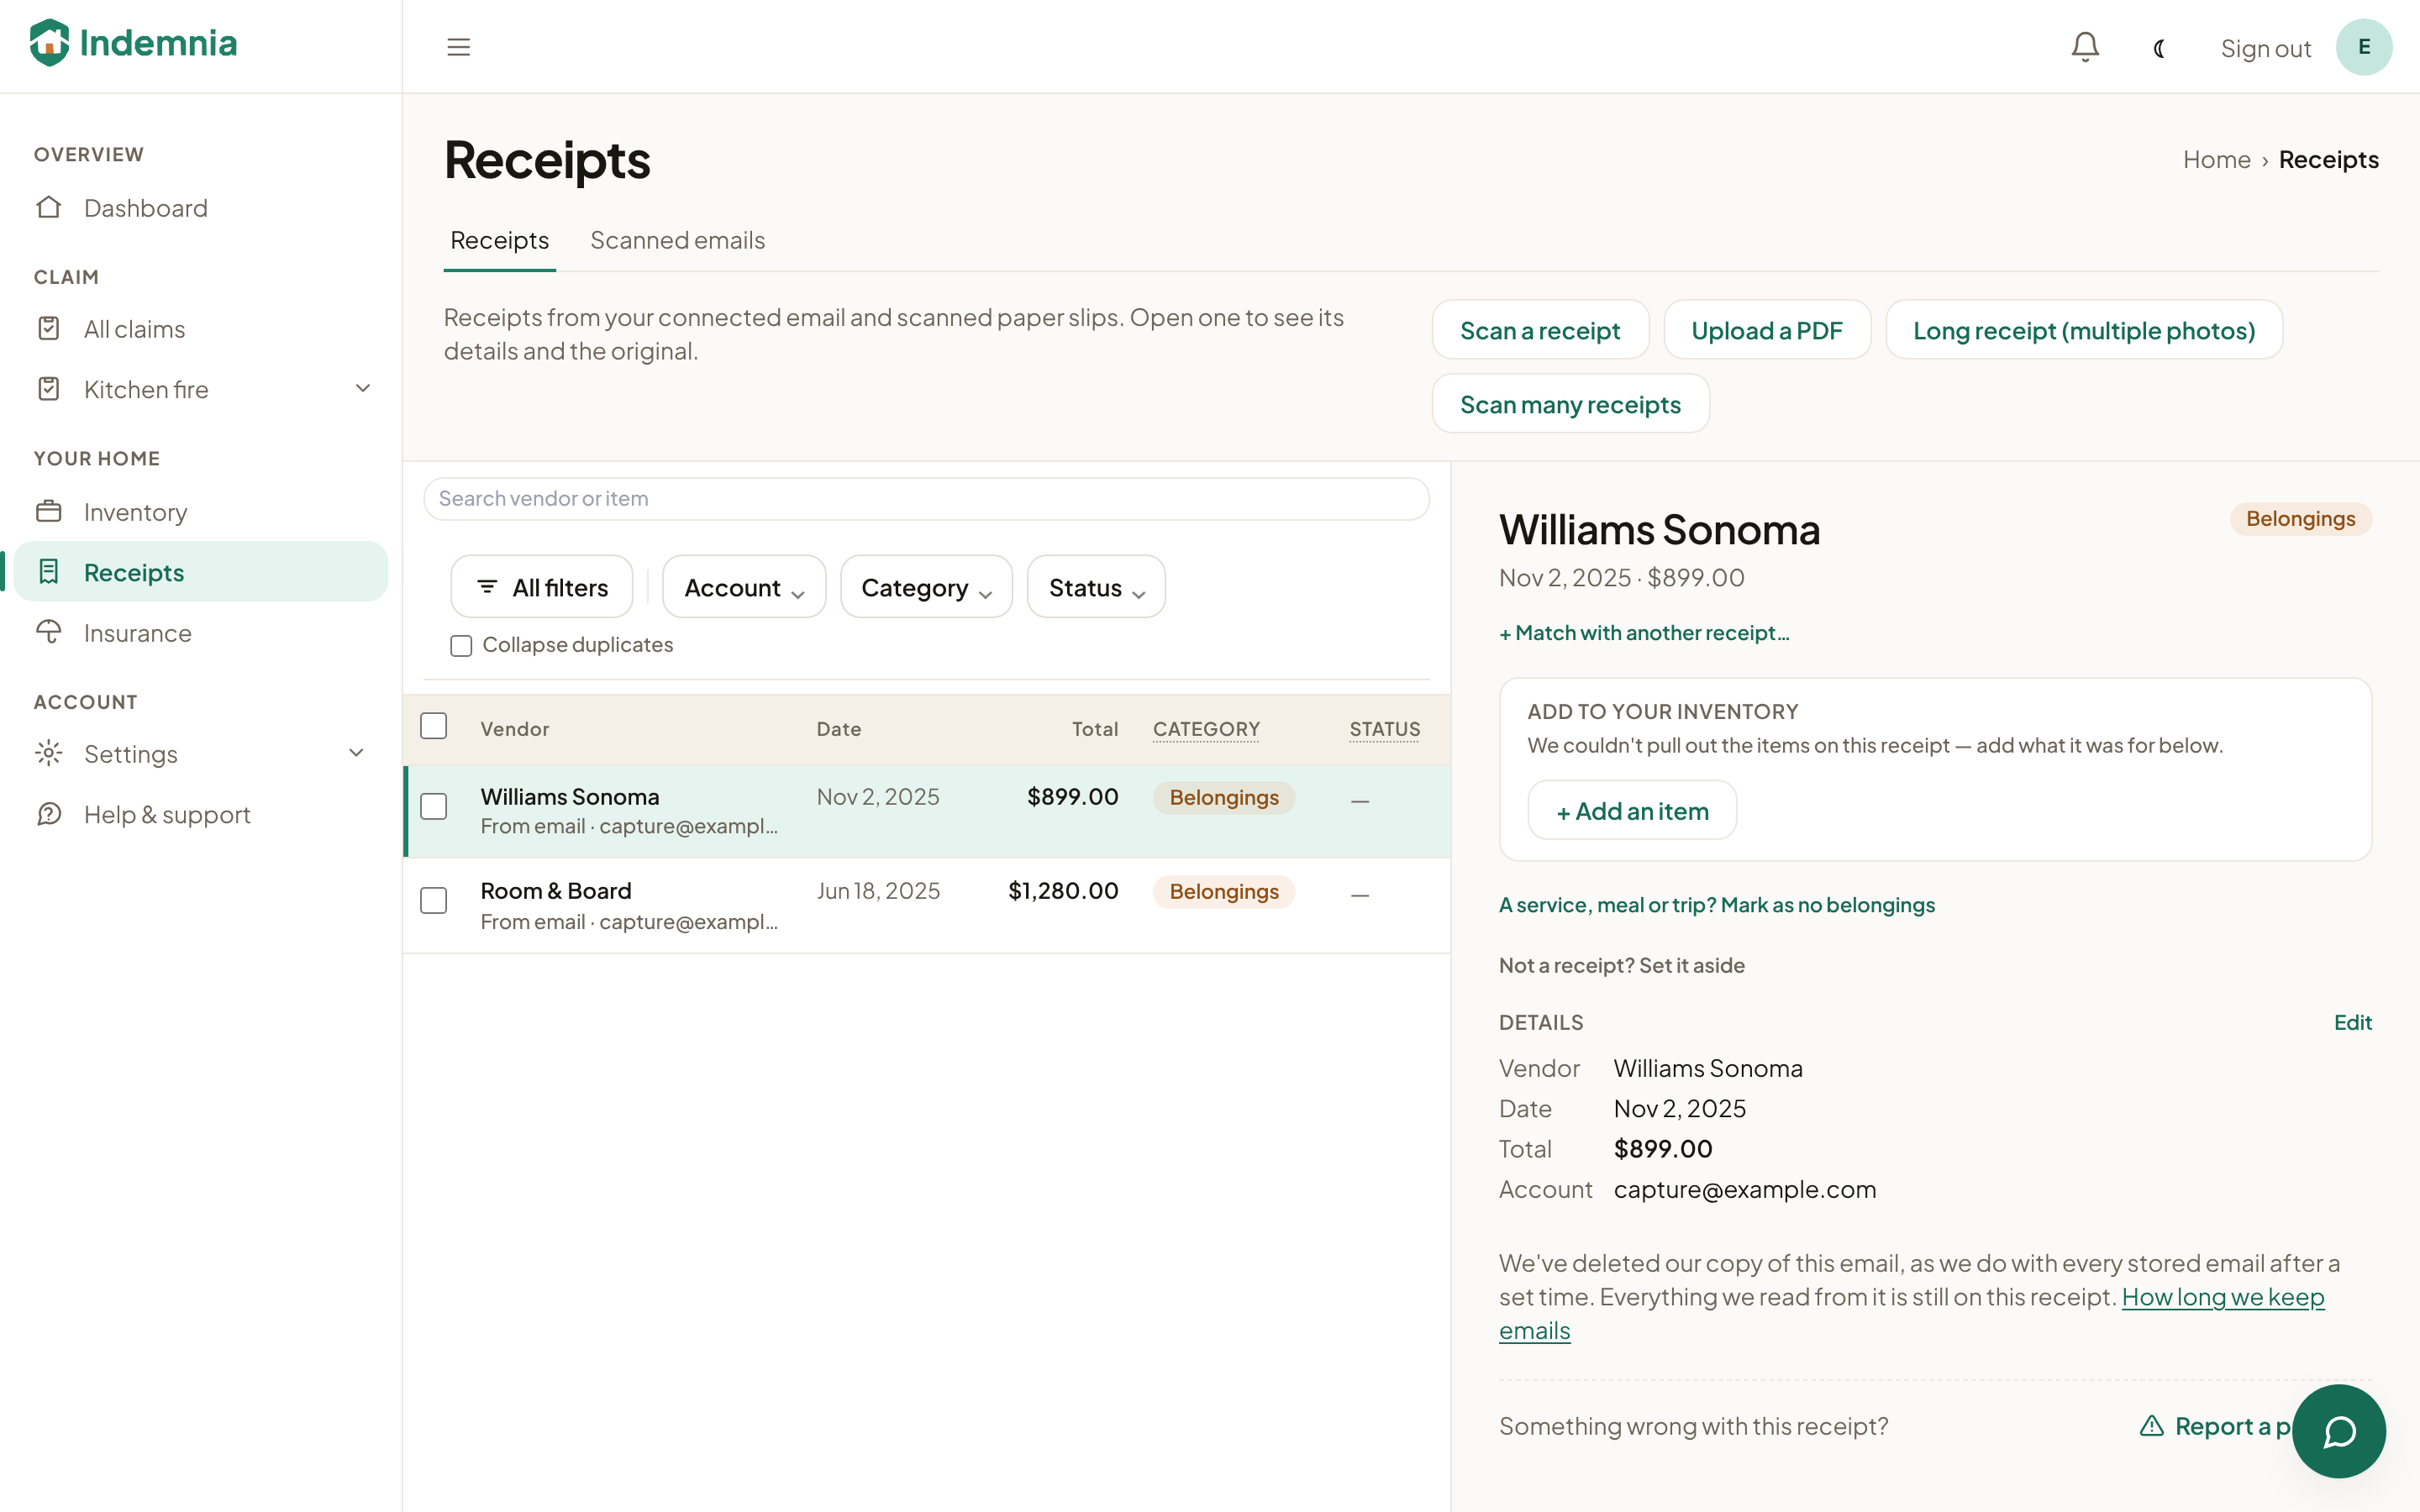
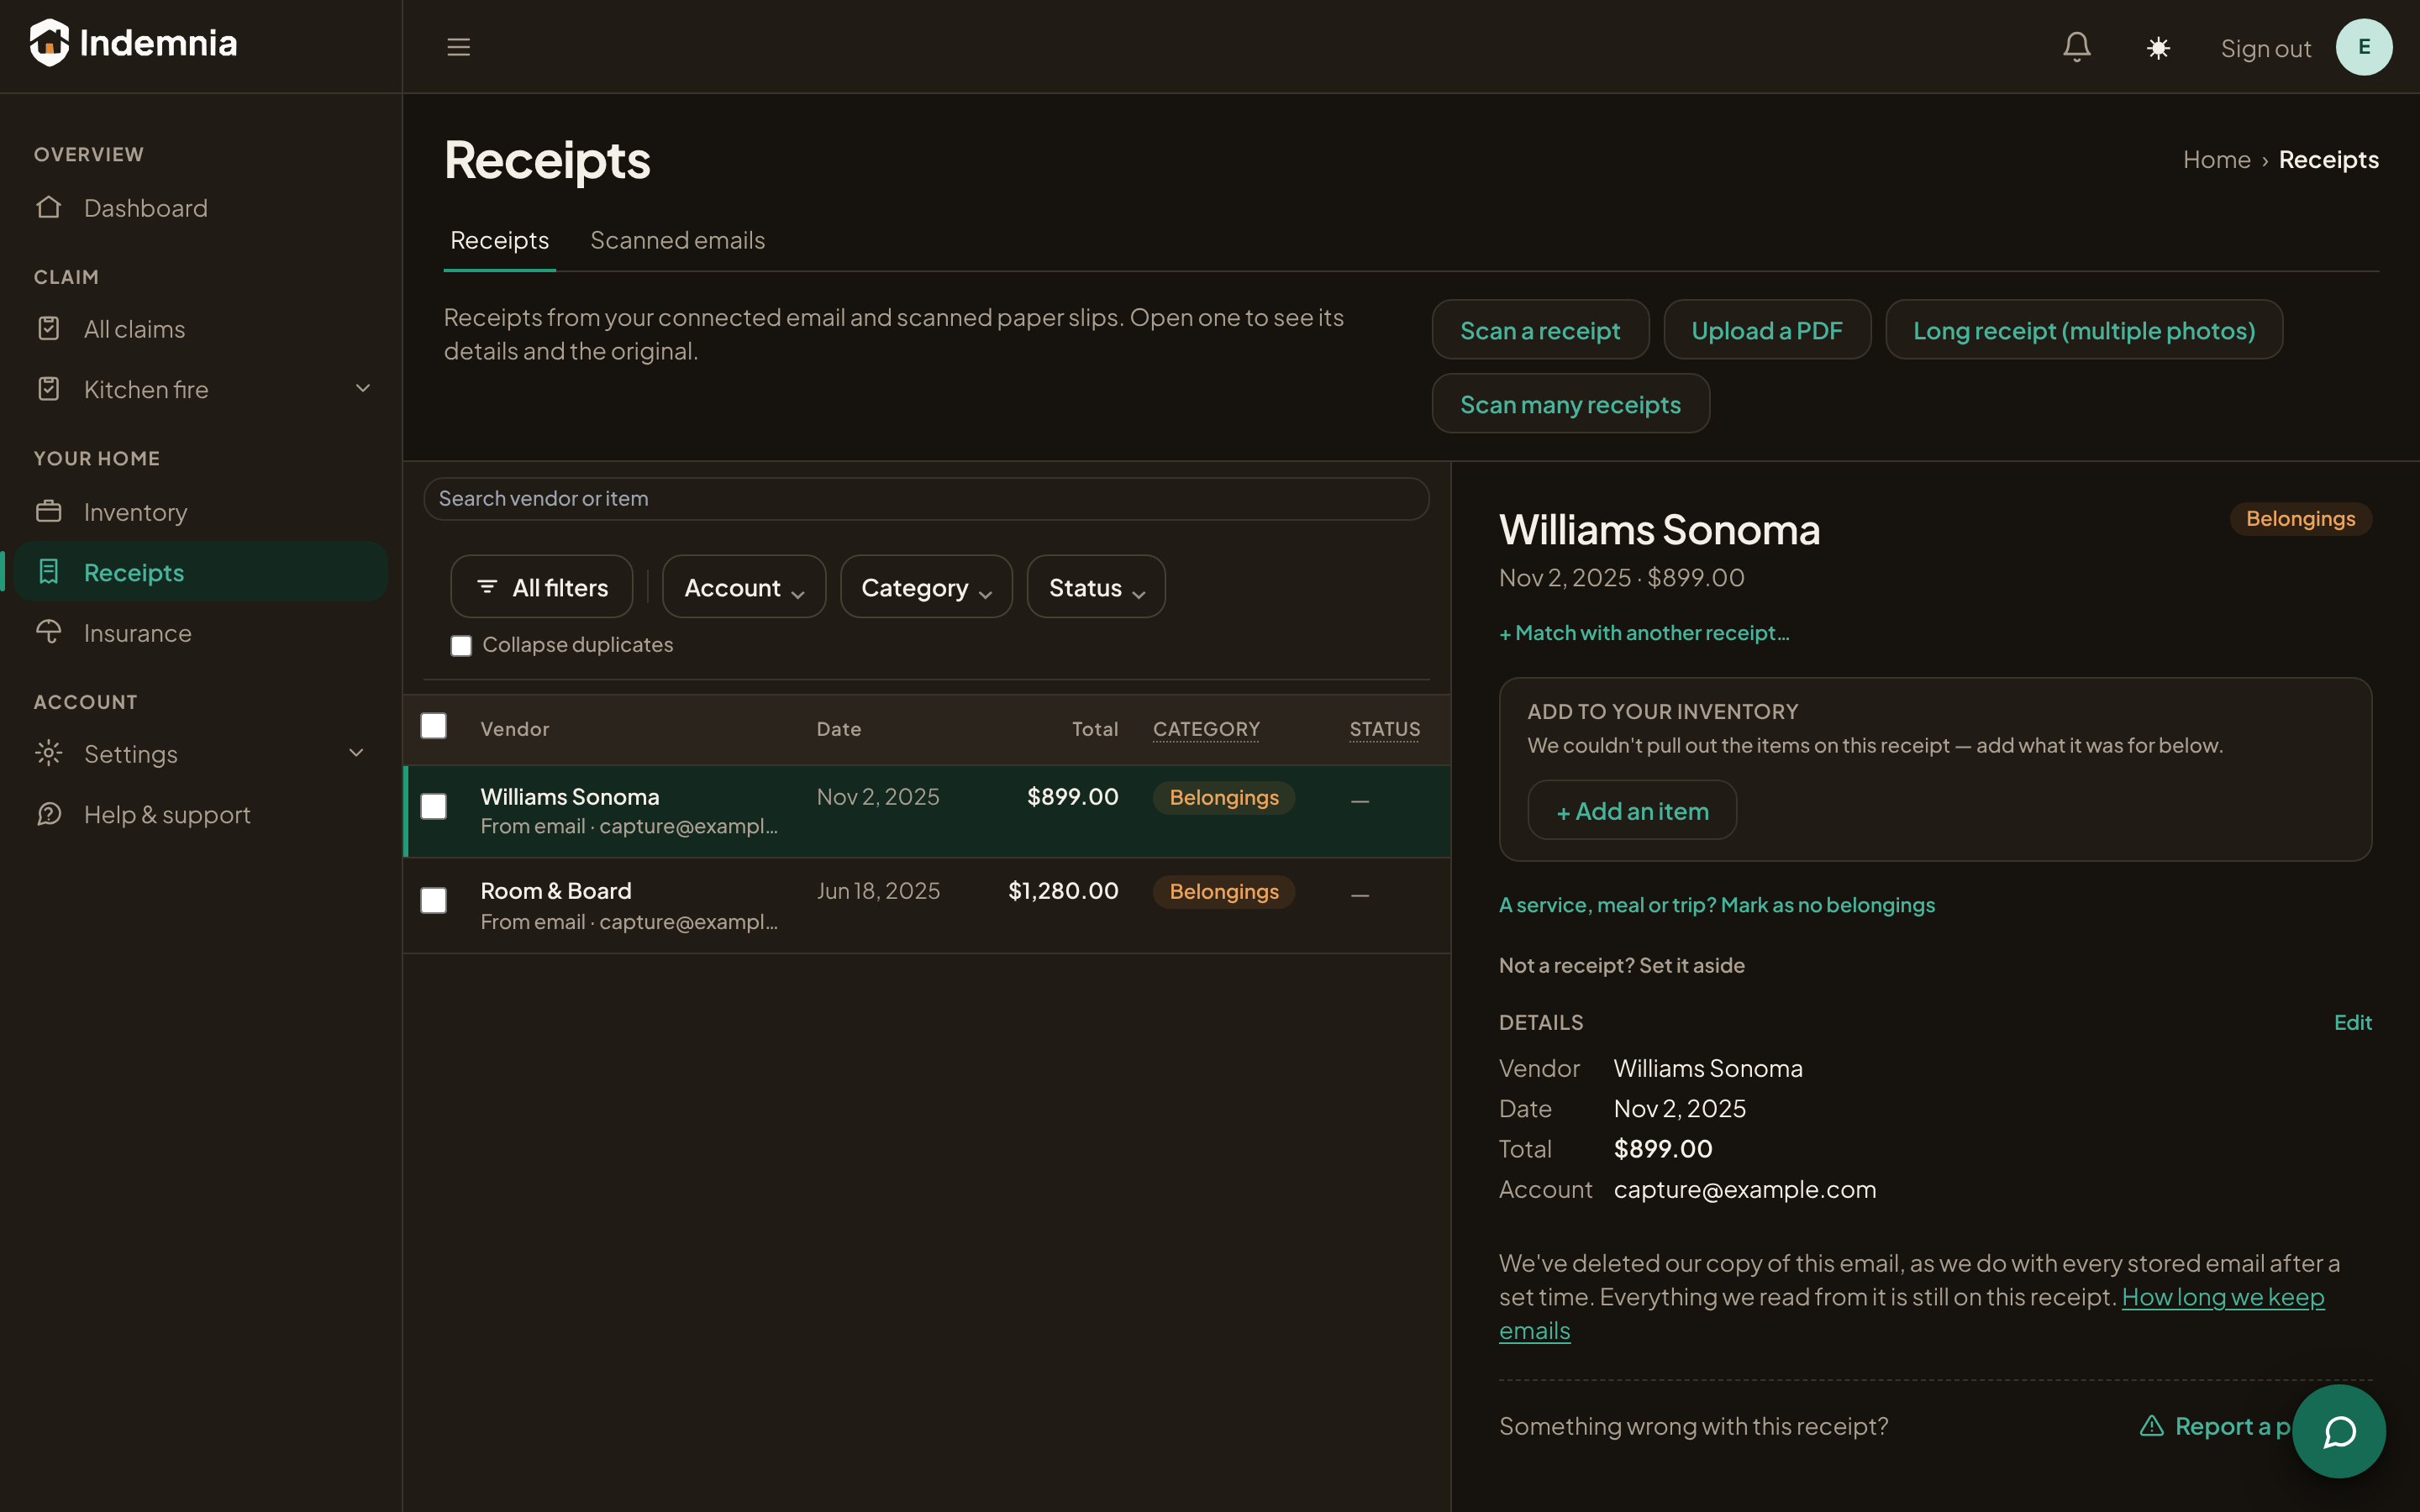
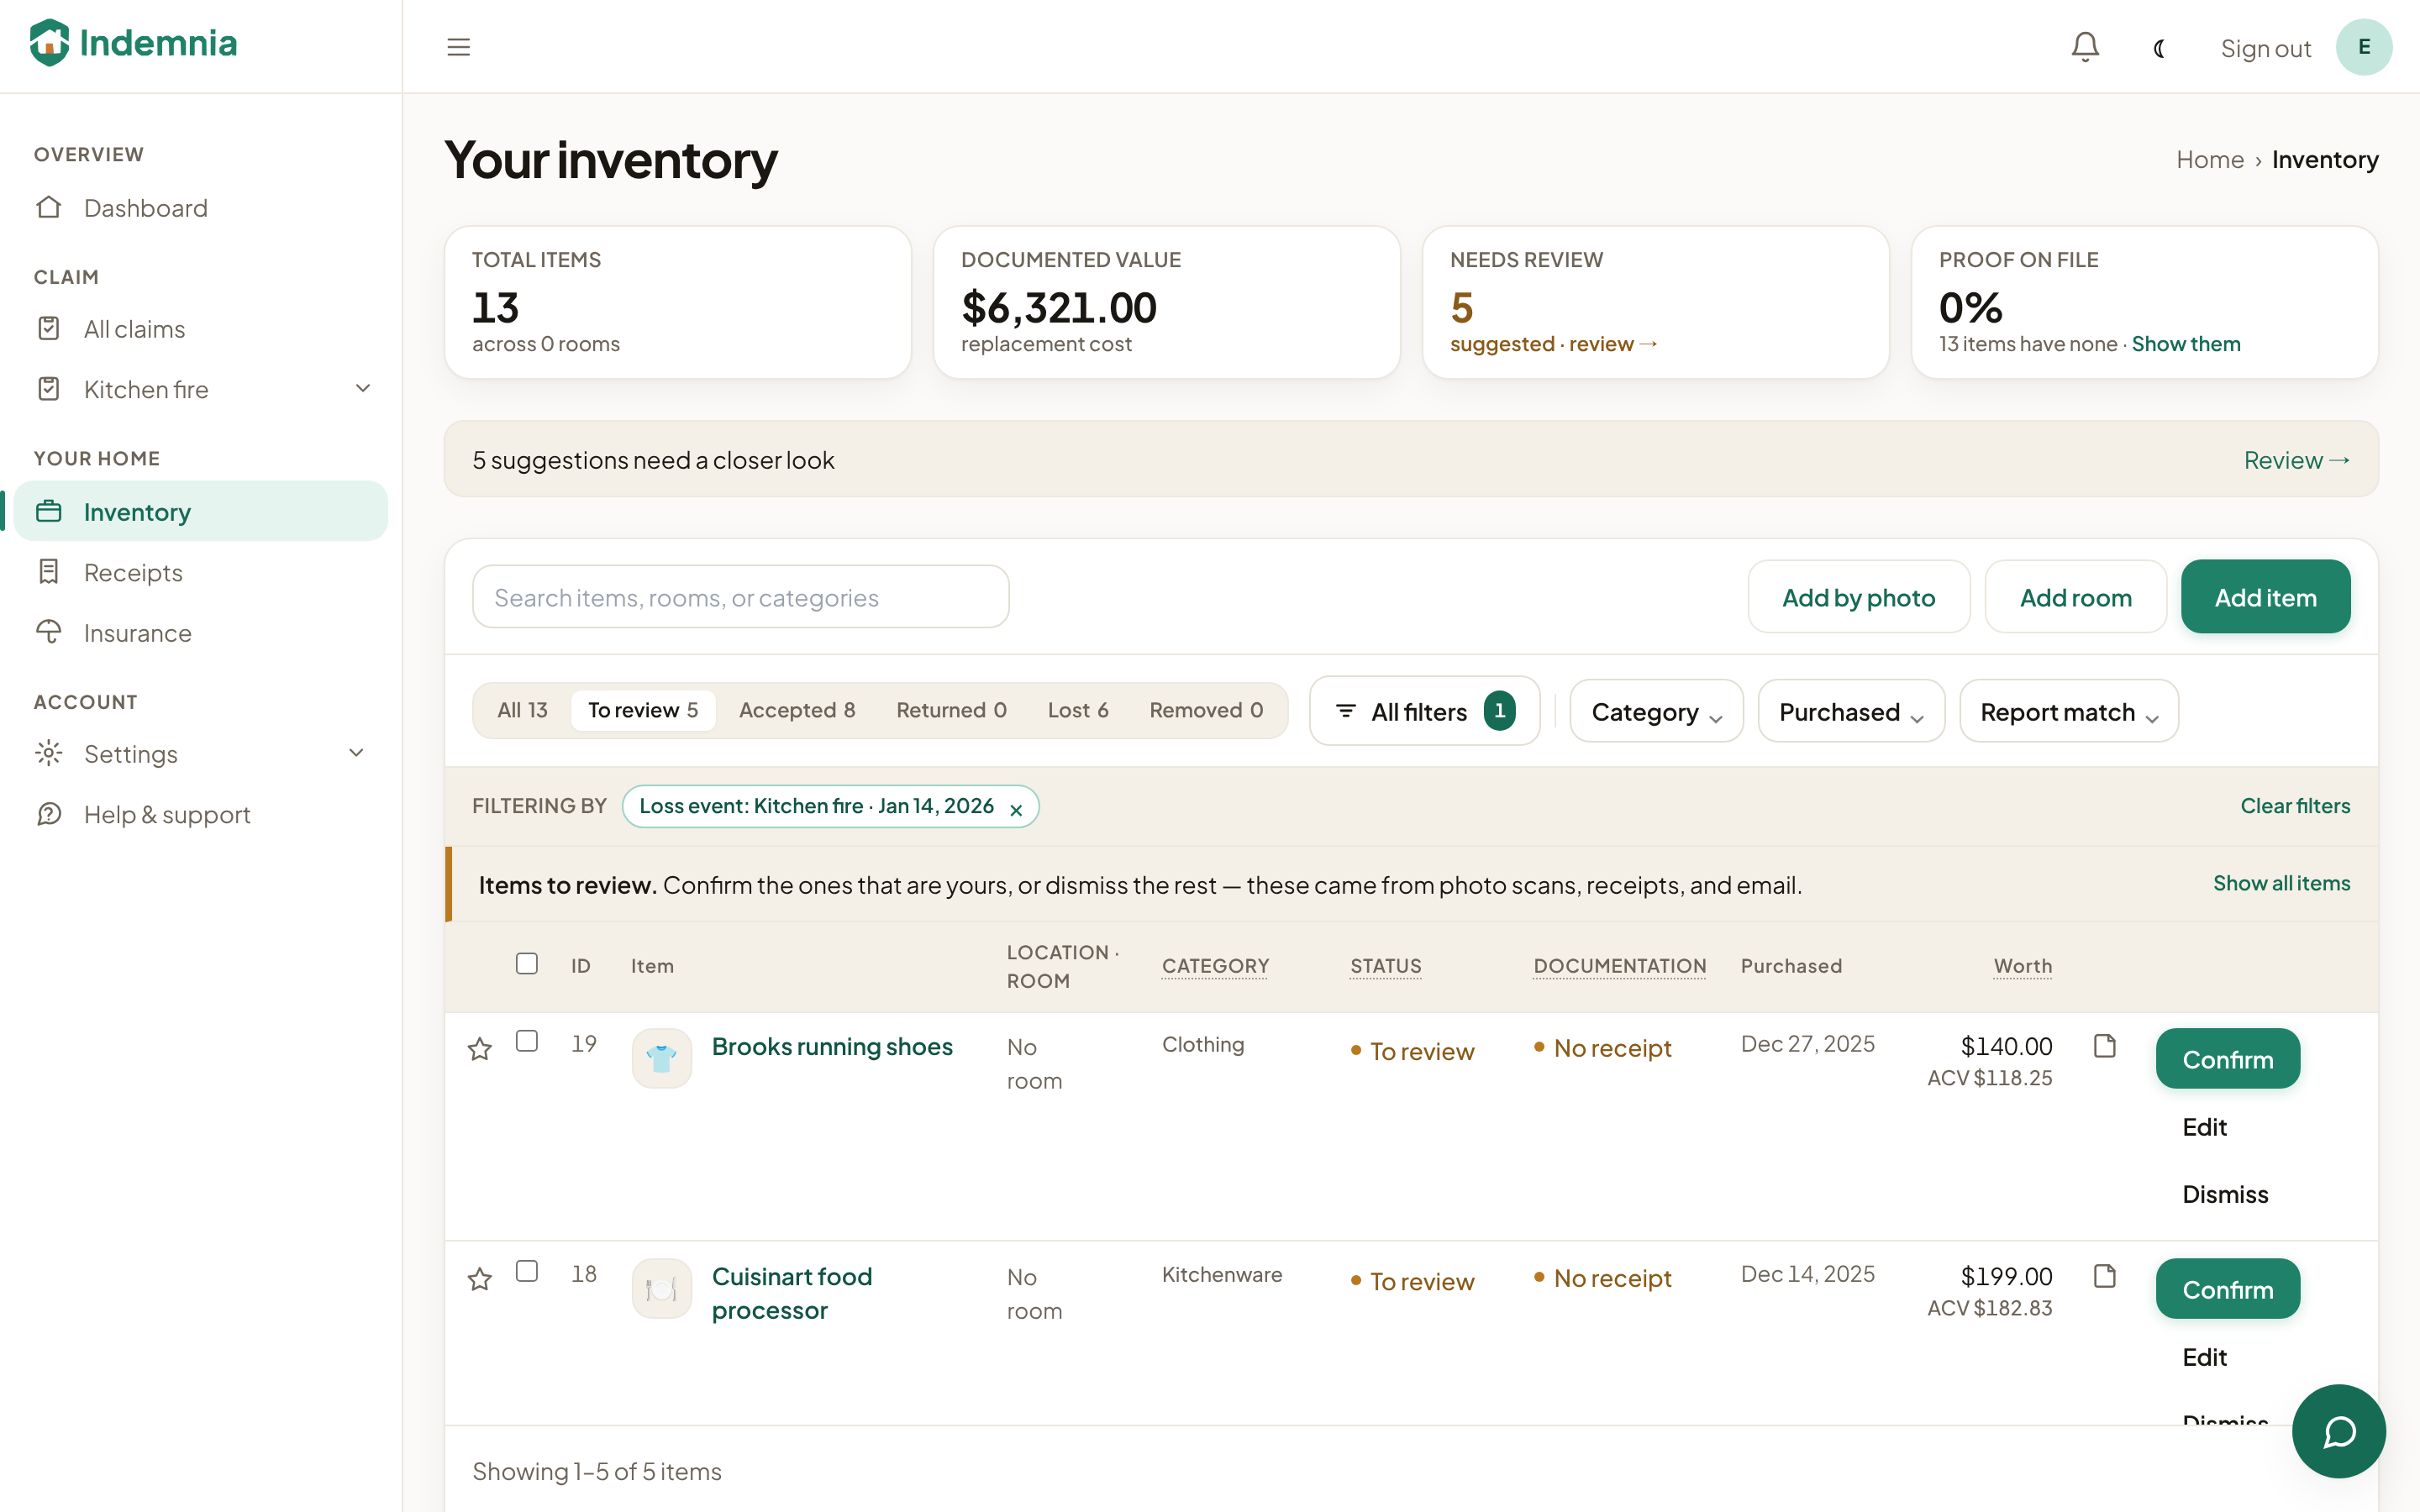
Nobody keeps a household inventory by hand. So Indemnia reads the receipts already sitting in your email, and you add what email never saw.
Two
Every figure has to trace to a document
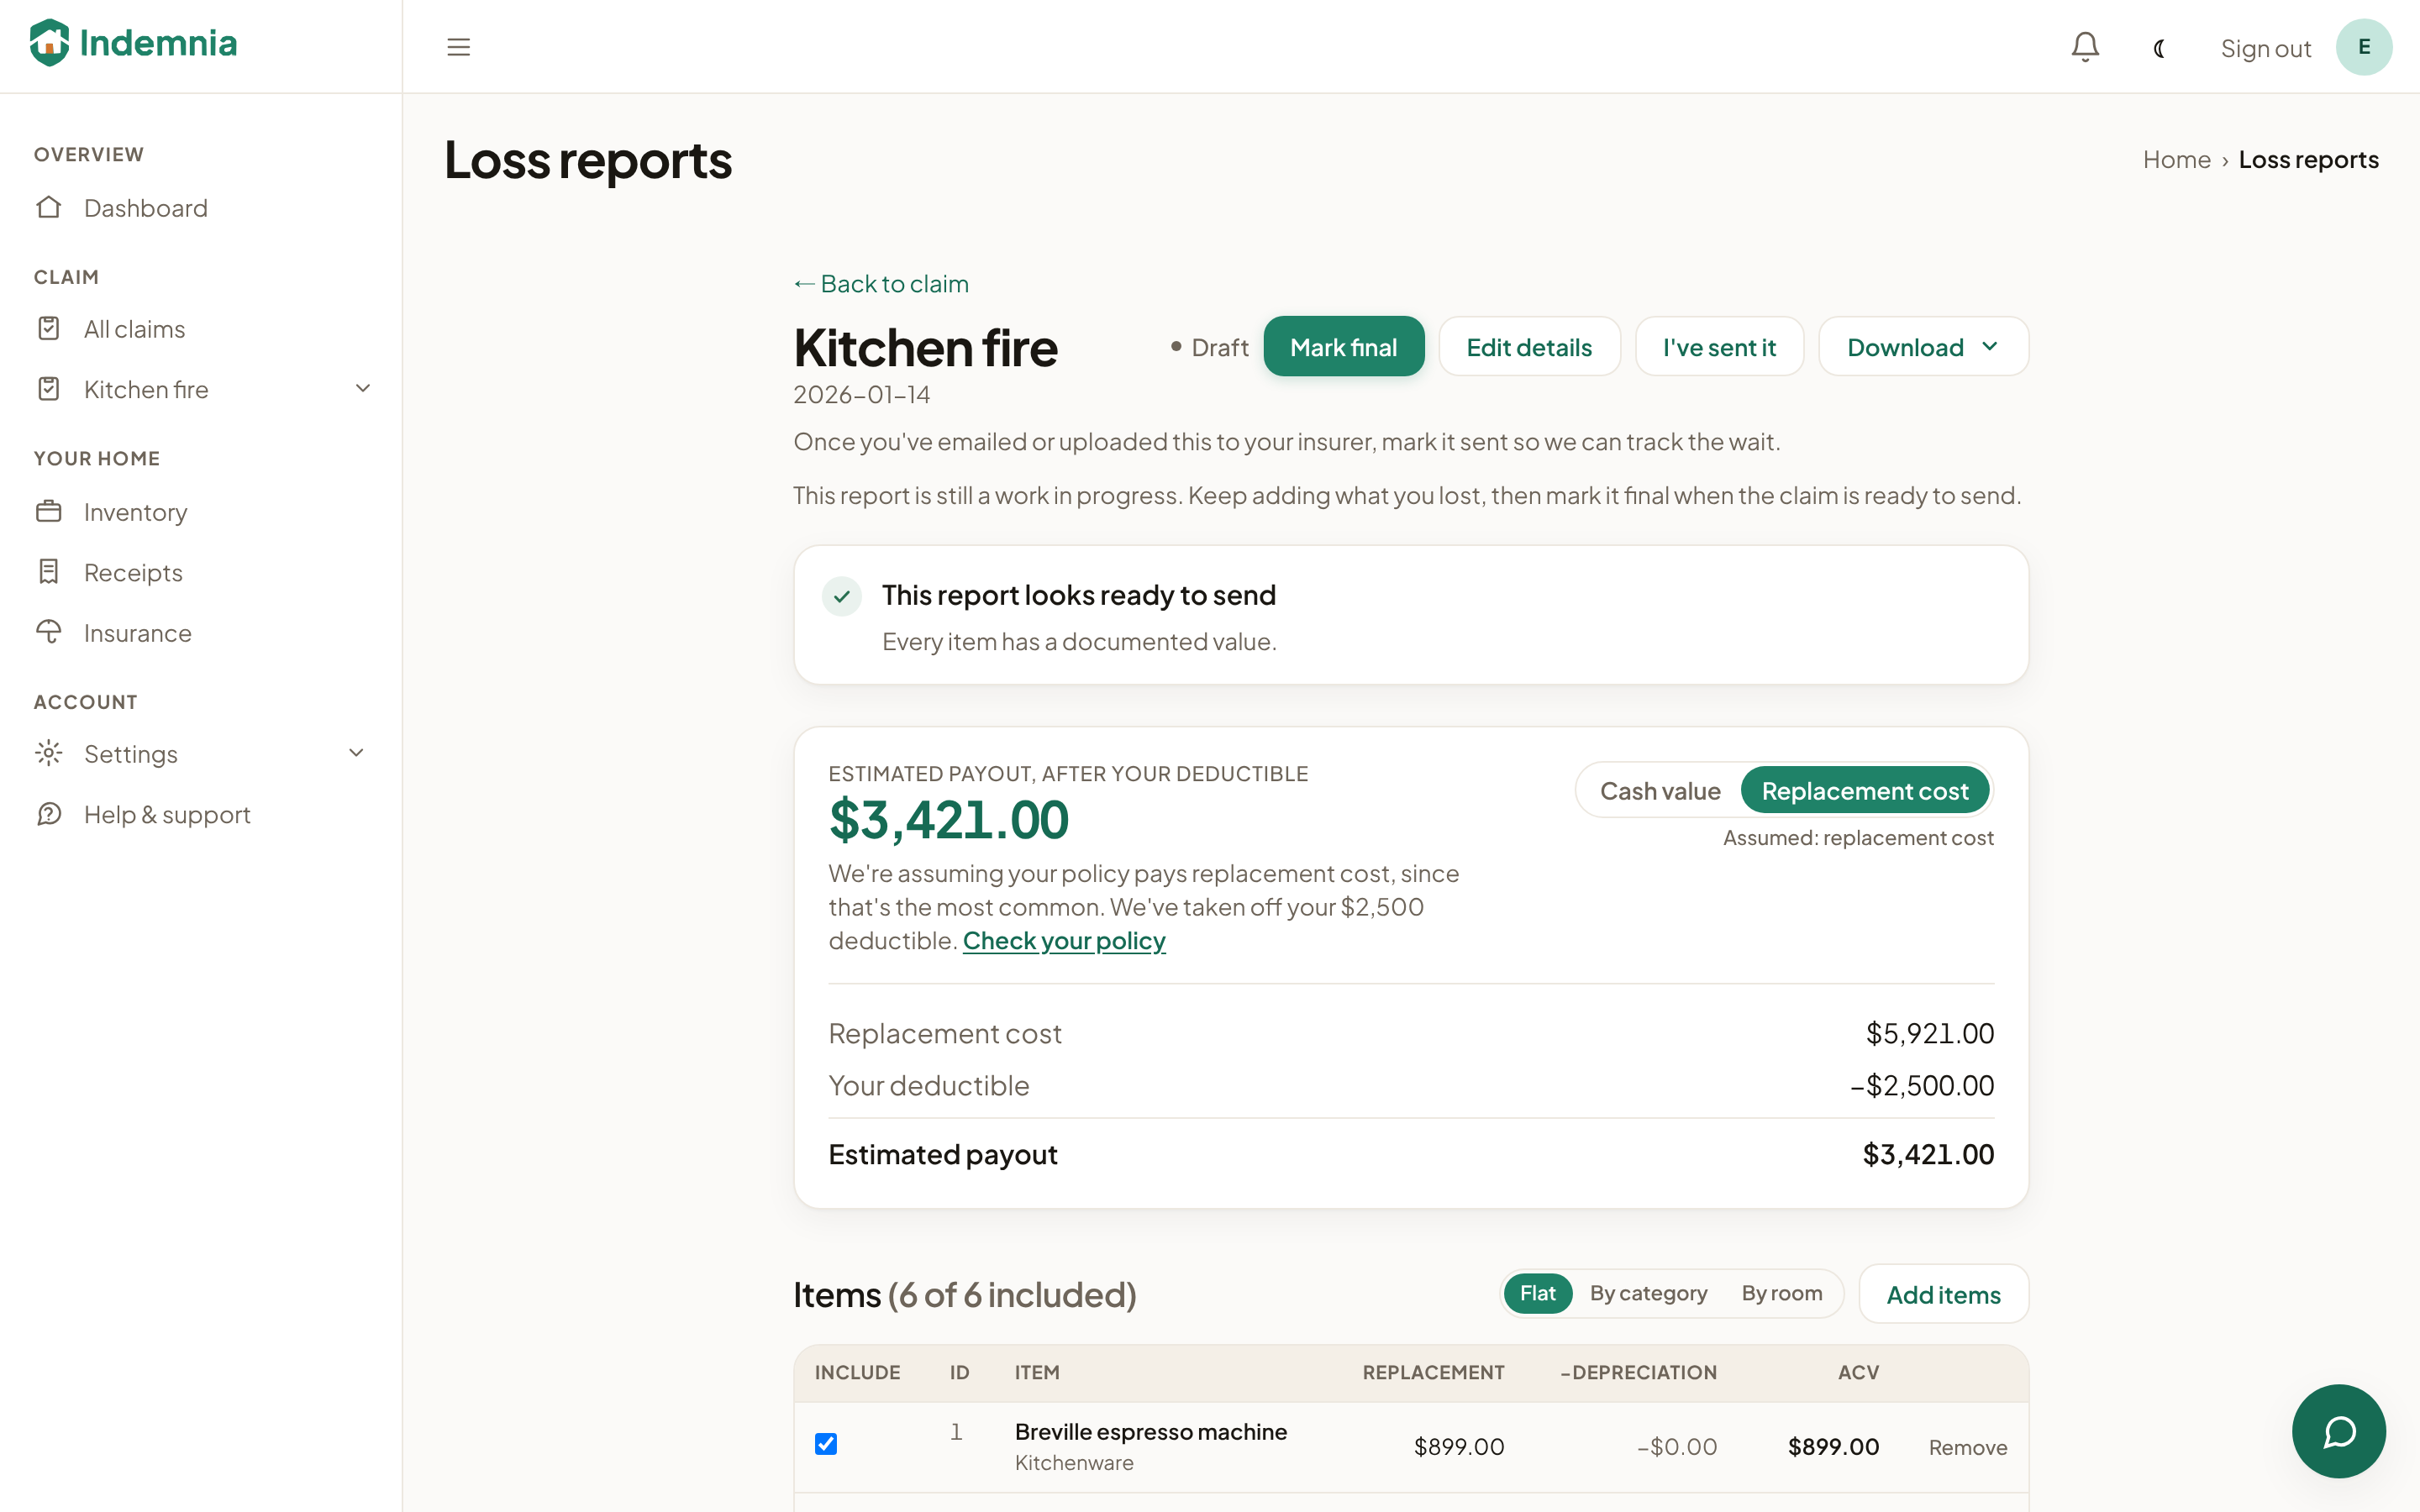
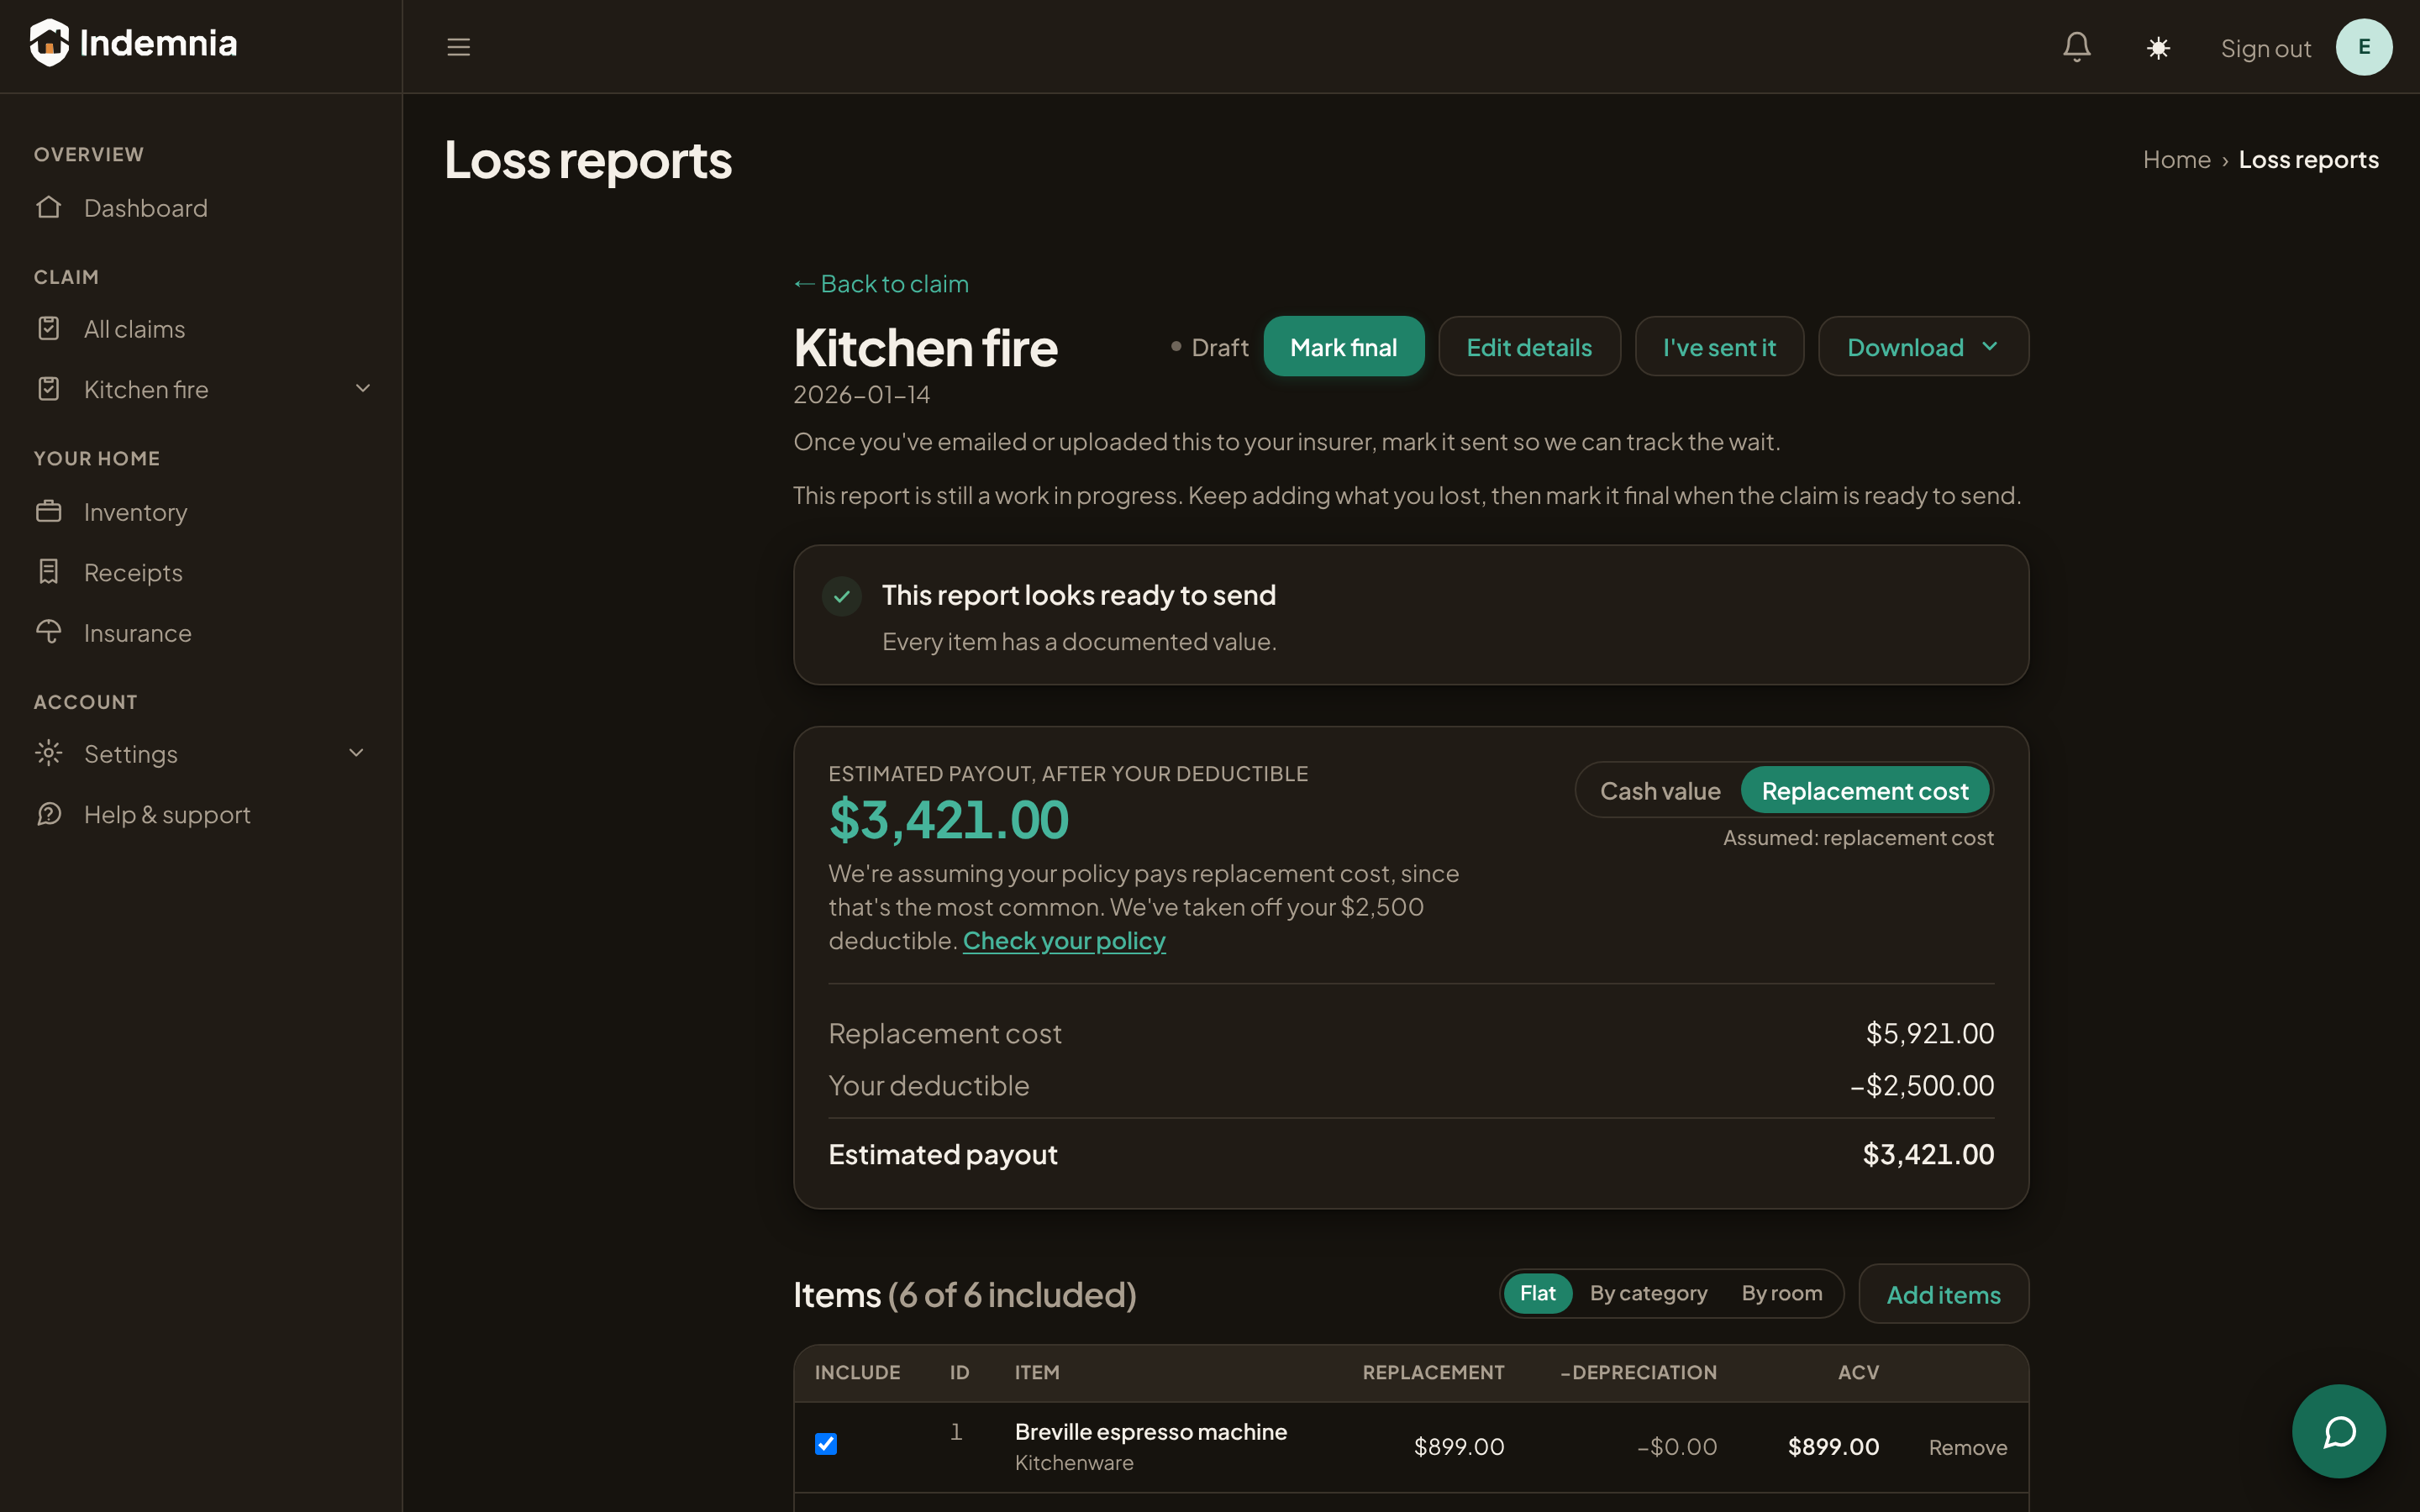
A schedule nobody can check gets argued with. Replacement cost, depreciation and actual cash value are shown per line, with the receipt attached to the line it proves.
Three
You decide what goes in
The review step isn't something we failed to automate away. It's the reason the record holds up when someone else checks it.
Why this side
We build for the person holding the blank form
The insurer arrives with an adjuster, software and a depreciation schedule of its own. The person who lost everything usually arrives with nothing written down. That gap is where a fair settlement gets hard, and it's the side of the table we work for.
Where we are
Early, and small on purpose. We're letting people in a few at a time, so the product is shaped by the first households and firms using it rather than around them. Everything you write to us is read by someone who can act on it.